Intel beat expectations in its third quarter of 2026, with its data center and AI business up 78%. But its forecast for the holiday quarter came in well below what analysts wanted, Intel warned that memory shortages are hurting PC sales, and the stock fell about 20% after hours on October 29. Here's what happened and what it means for PC buyers.
This page has affiliate links: if you buy through them, WIZY may earn a small commission at no extra cost to you. As an Amazon Associate I earn from qualifying purchases.
This is news, not financial advice. Do your own research before buying or selling any stock.
The numbers
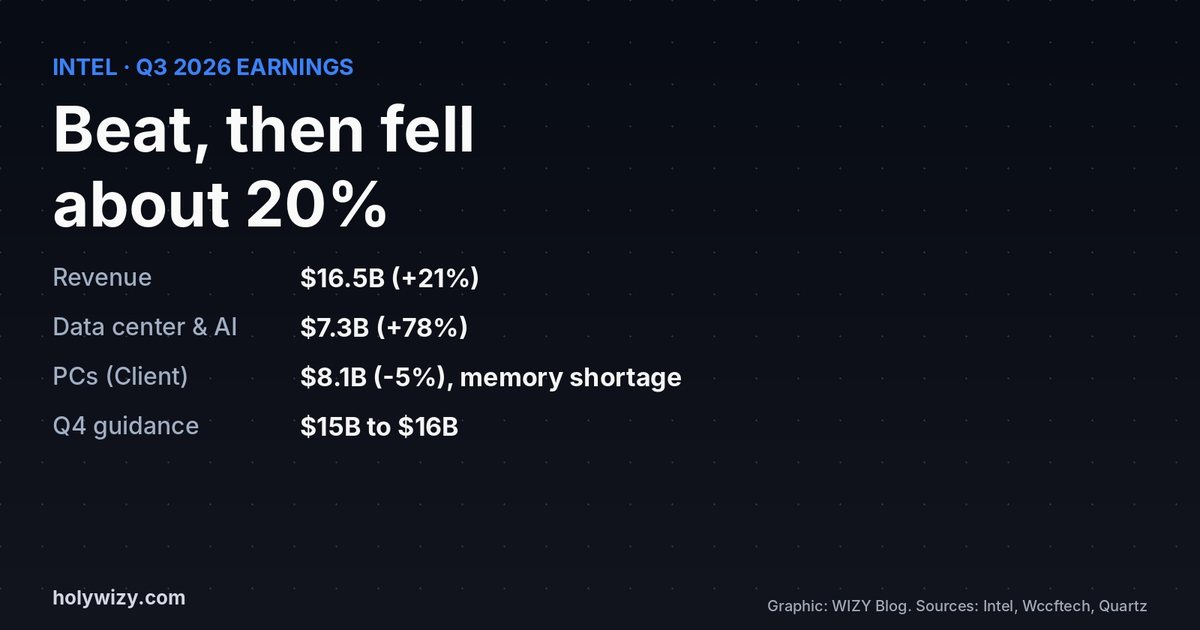
- Revenue: $16.5 billion, up 21% from a year ago.
- Earnings per share (non-GAAP): $0.52, well above the roughly $0.40 analysts expected.
- Data Center and AI: $7.3 billion, up 78%, with operating income of about $3.0 billion, more than triple a year ago.
- Client Computing (PCs): $8.1 billion, down 5%.
- Foundry: revenue up 58%, though the foundry business still lost money.
- Gross margin: 43.0%, up from 38.2% (44.1% non-GAAP).
Why the stock fell
The problem was the outlook. Intel expects fourth-quarter revenue of $15.0 billion to $16.0 billion, below the roughly $17 billion analysts expected, and a gross margin of about 38%. Reports put the after-hours drop at roughly 20% or more, with Quartz citing over 22%. After-hours moves can change by the next open.
What it means for PC buyers
Intel blamed the PC slowdown on memory shortages: AI data centers are buying up so much memory that there's less left for regular PCs, which pushes RAM and PC prices up. Management said the PC slowdown will likely last at least through the first half of 2027. That matches what we've seen all month, from SK Hynix's record profit to RAM prices for gamers.
If you're planning a PC upgrade, it may be worth buying the memory and storage you need sooner rather than later, and watching for Black Friday deals.
The bigger picture
It's the same story as Alphabet and Amazon this week: AI demand is booming, but investors are punishing anything that looks weaker going forward. Intel's AI data center growth was huge; its PC business, squeezed by the AI memory rush, is what spooked the market. See also our Amazon earnings article.
My take
A 78% jump in data center revenue is a big turnaround sign for Intel, but if PCs stay weak into 2027 because AI is eating all the memory, gamers and PC buyers will feel it in prices. Are you holding off on upgrading, or buying before prices rise further?
Sources
- Wccftech: Intel's data center business is now almost as big as its PC division wccftech.com
- Quartz: Intel stock falls more than 22% after Q3 2026 earnings qz.com
- Shacknews: Intel Q3 2026 earnings results shacknews.com
- 24/7 Wall St.: Intel Q3 2026, data center revenue surges 78% 247wallst.com
- Intel Q3 2026 earnings release (SEC) sec.gov
Written by the WIZY creator
An independent builder on Monad, working on the WIZY project and the WIZY RPG game. I write about crypto in plain English and about the games I care about, and I check every fact against its source.